
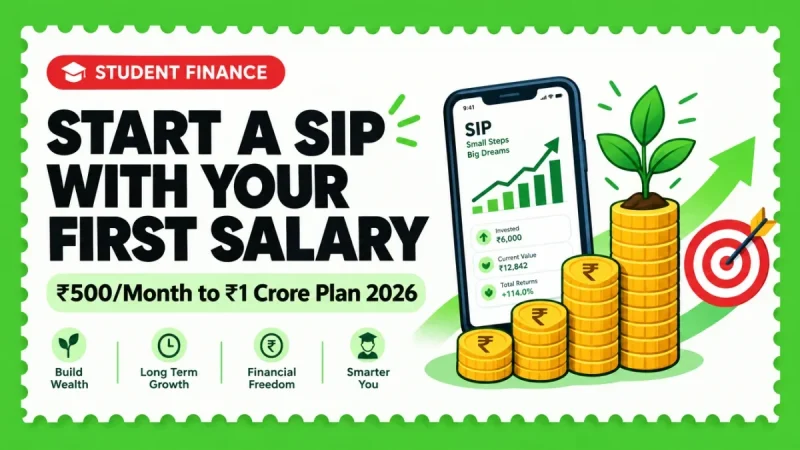
Your first salary feels small — but your biggest investing advantage is time, and no one will ever have more of it than you do today. Here's the fresher's SIP playbook: which fund, which app, how much, and the compounding math.
How should a fresher start a SIP with their first salary? Complete KYC with PAN + Aadhaar on a free direct-plan app (Groww, Zerodha Coin, Kuvera or Paytm Money), pick one Nifty 50 index fund — direct plan, growth option — and set an auto-debit SIP of at least ₹500–₹2,000 for 2–3 days after salary day. Aim to invest around 20% of your in-hand salary, increase the SIP by 10% every year, and don't stop when markets fall. At an assumed 12% return, ₹5,000/month grows to roughly ₹1.76 crore in 30 years.
⏳ Why Your First Salary Is Your Biggest Investing Advantage
Here's the uncomfortable truth about money: starting age matters more than salary. A fresher investing ₹3,000/month from age 22 ends up with more than someone investing ₹10,000/month from age 35 — because compounding rewards time, not amounts.
Just sorted your tax? Good — read how freshers save tax on their first salary (FY 2026-27) first, because most freshers pay zero tax under the new regime, which means more money free to invest.
📖 SIP in 60 Seconds — What It Actually Is
A SIP (Systematic Investment Plan) is simply an auto-debit that invests a fixed amount into a mutual fund every month. A mutual fund pools money from lakhs of investors and buys shares. An index fund is the simplest type — it blindly copies an index like the Nifty 50 (India's 50 biggest companies: Reliance, HDFC Bank, Infosys, TCS…), so there's no fund manager making bets, and costs stay tiny.
| Term | Meaning for you |
|---|---|
| NAV | Price of one unit of the fund — your SIP buys units at each month's NAV |
| Expense ratio | Yearly fee cut from your money. Index funds: ~0.1–0.3%. Active funds: 1–2% |
| Direct plan | No distributor commission — compounds ~1% faster than "regular" plans |
| Growth option | Profits stay invested (choose this), instead of being paid out as IDCW/dividend |
| Rupee cost averaging | Fixed SIP buys more units when markets fall, fewer when they rise — averages your cost |
| Step-up SIP | SIP that auto-increases every year (e.g., +10%) as your salary grows |
🧮 The Compounding Math — What Your SIP Becomes
Assuming a 12% annual return (roughly the long-term historical average of Indian equity — not guaranteed, markets go up and down):
| Monthly SIP | 10 years | 20 years | 30 years | You invested (30 yrs) |
|---|---|---|---|---|
| ₹500 | ≈ ₹1.16 L | ≈ ₹5 L | ≈ ₹17.6 L | ₹1.8 L |
| ₹2,000 | ≈ ₹4.6 L | ≈ ₹20 L | ≈ ₹70.6 L | ₹7.2 L |
| ₹5,000 | ≈ ₹11.6 L | ≈ ₹50 L | ≈ ₹1.76 Cr | ₹18 L |
| ₹10,000 | ≈ ₹23.2 L | ≈ ₹1 Cr | ≈ ₹3.53 Cr | ₹36 L |
Read the ₹5,000 row again: you put in ₹18 lakh over 30 years, and compounding adds ₹1.58 crore on top. That's why starting at 22 instead of 32 is worth more than any salary hike.
🪜 Start Your First SIP — 5 Steps This Weekend
⚖️ SIP vs FD vs RD — Where Should a Fresher's Money Go?
| Feature | Equity SIP (index fund) | Fixed deposit | Recurring deposit |
|---|---|---|---|
| Typical returns | ~10–12% long term (market-linked) | ~6–7.5% (fixed) | ~6–7% (fixed) |
| Risk | Falls in crashes; smooths out over 7+ yrs | Almost none | Almost none |
| Beats inflation? | ✅ Usually, over long term | Barely | Barely |
| Lock-in | None (ELSS: 3 yrs) | Penalty on early exit | Fixed tenure |
| Best for | Goals 5+ years away, wealth building | Emergency fund, short-term goals | Forced saving for 1–2 yr goals |
Fresher formula: emergency fund in FD/savings → long-term wealth in equity SIP. Both have jobs; neither replaces the other. Taking the old tax regime? An ELSS fund SIP gives equity returns plus a Section 80C deduction (3-year lock-in) — details in our fresher tax guide.
🚫 5 SIP Mistakes Freshers Make
🧾 Taxes on SIP — The 2-Minute Version
When you eventually sell equity fund units: gains on units held over 12 months are LTCG — taxed at 12.5% on gains above ₹1.25 lakh per year. Units sold within 12 months attract 20% STCG. While you're only investing (not selling), there's no tax at all — one more reason to buy and hold. Rules can change; check before redeeming.
Want to go deeper into funds and stock investing? Read mutual funds for beginners in India, best demat accounts in India and best investments for young professionals. And once your SIP is running, put your spending on a rewards card — here's how freshers get their first credit card and build a 750+ CIBIL score.
- Freshers can start a SIP with ₹500/month (many funds allow ₹100); recommended first fund: Nifty 50 index fund, direct plan, growth option, expense ratio under 0.3%.
- Free direct-plan platforms: Groww, Zerodha Coin, Kuvera, Paytm Money; KYC needs PAN + Aadhaar + bank account.
- At an assumed 12% return: ₹5,000/month ≈ ₹1.76 crore in 30 years (₹18L invested); 10% yearly step-up reaches ₹1 crore in ~21–22 years.
- Ideal allocation: ~20% of in-hand salary (50/30/20 rule); build a 3–6 month emergency fund in FD/liquid funds before equity SIPs.
- Equity taxation: LTCG 12.5% on gains above ₹1.25L/year after 12 months; STCG 20% within 12 months; no tax while holding.
- Never stop SIPs in crashes — rupee cost averaging buys more units at lower prices.